
- Mortgage applications fell 4.2% for the week ending Oct. 2 amid rising rates.
- Freddie Mac reported a 7.4% weekly average rate for 30-year fixed mortgages.
- Adjustable-rate mortgages now account for over 10% of applications, highest in a year.
SALT LAKE CITY — Fewer Americans are seeking to borrow money to buy homes as mortgage rates continue to climb.
Mortgage applications were down 4.2% across the United States for the week ending Oct. 2, according to the latest survey by the Mortgage Bankers Association that uses seasonally adjusted data.
"Mortgage rates moved to their highest level in almost three years last week," Joel Kan, the association's vice president and deputy chief economist, said Wednesday, noting the jump "has caused many potential borrowers to step back from the purchase market."
The Federal Home Loan Mortgage Corporation, better known as Freddie Mac, posted a 7.4% weekly average rate for a 30-year fixed-rate mortgage Thursday. Up 0.12 percentage points from the prior week, the weekly rate is the highest since November 2023.
Kan said very few current homeowners "have an incentive to refinance at these rates." The association's index for refinancing applications showed an even larger drop from the previous week, 8%, and was down 56% from the same week one year ago.
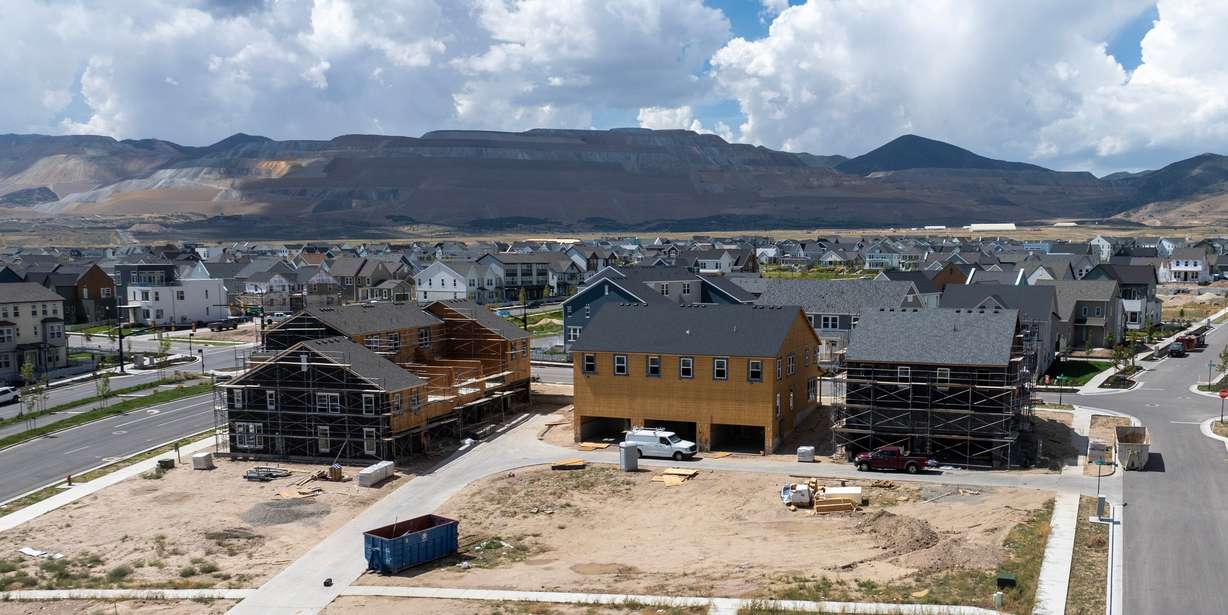
More buyers are opting for adjustable-rate mortgages to initially lower their payments, Kan said.
Commonly called ARMs, they now account for just over 10% of all mortgage applications, according to the association. That's the highest share in about a year and up from 7% at the beginning of 2026, Realtor.com reported.
For a mortgage that starts with a set rate for five years and then is annually adjusted up or down to align with current market conditions, the association put the average rate at 6.43% for the week ending Oct. 2, more than a percentage point lower than a fixed-rate loan.
Some buyers priced out of fixed-rate borrowing still can afford the lower initial payments available through the once popular adjustable-rate mortgage, Realtor.com senior economist Hannah Jones said.
"Increasingly, it may simply be the only way some buyers can enter the market at all," Jones said. She calculated about a $178 reduction in the monthly principal and interest payment on a $400,000 home with 20% down and financed through an ARM, based on recent rates.
However, as many buyers learned during the 2008 financial crisis, monthly payments may not remain affordable after the rates begin adjusting. Then, rate resets pushed a typical borrower's monthly payment up by nearly $580 in today's dollars, Realtor.com said.
Although homebuyers using an adjustable-rate mortgage will save money initially that can be used to cushion the impact of future mortgage rate increases, Jones said they need to understand just how much higher their payments could be under their loan terms.
"Can your budget absorb a significant jump in your monthly mortgage payment?" she said. "If not, the ARM may not be the right product for you."